
Who needs humanoids? Direct Drive Tech bets on simpler household robots
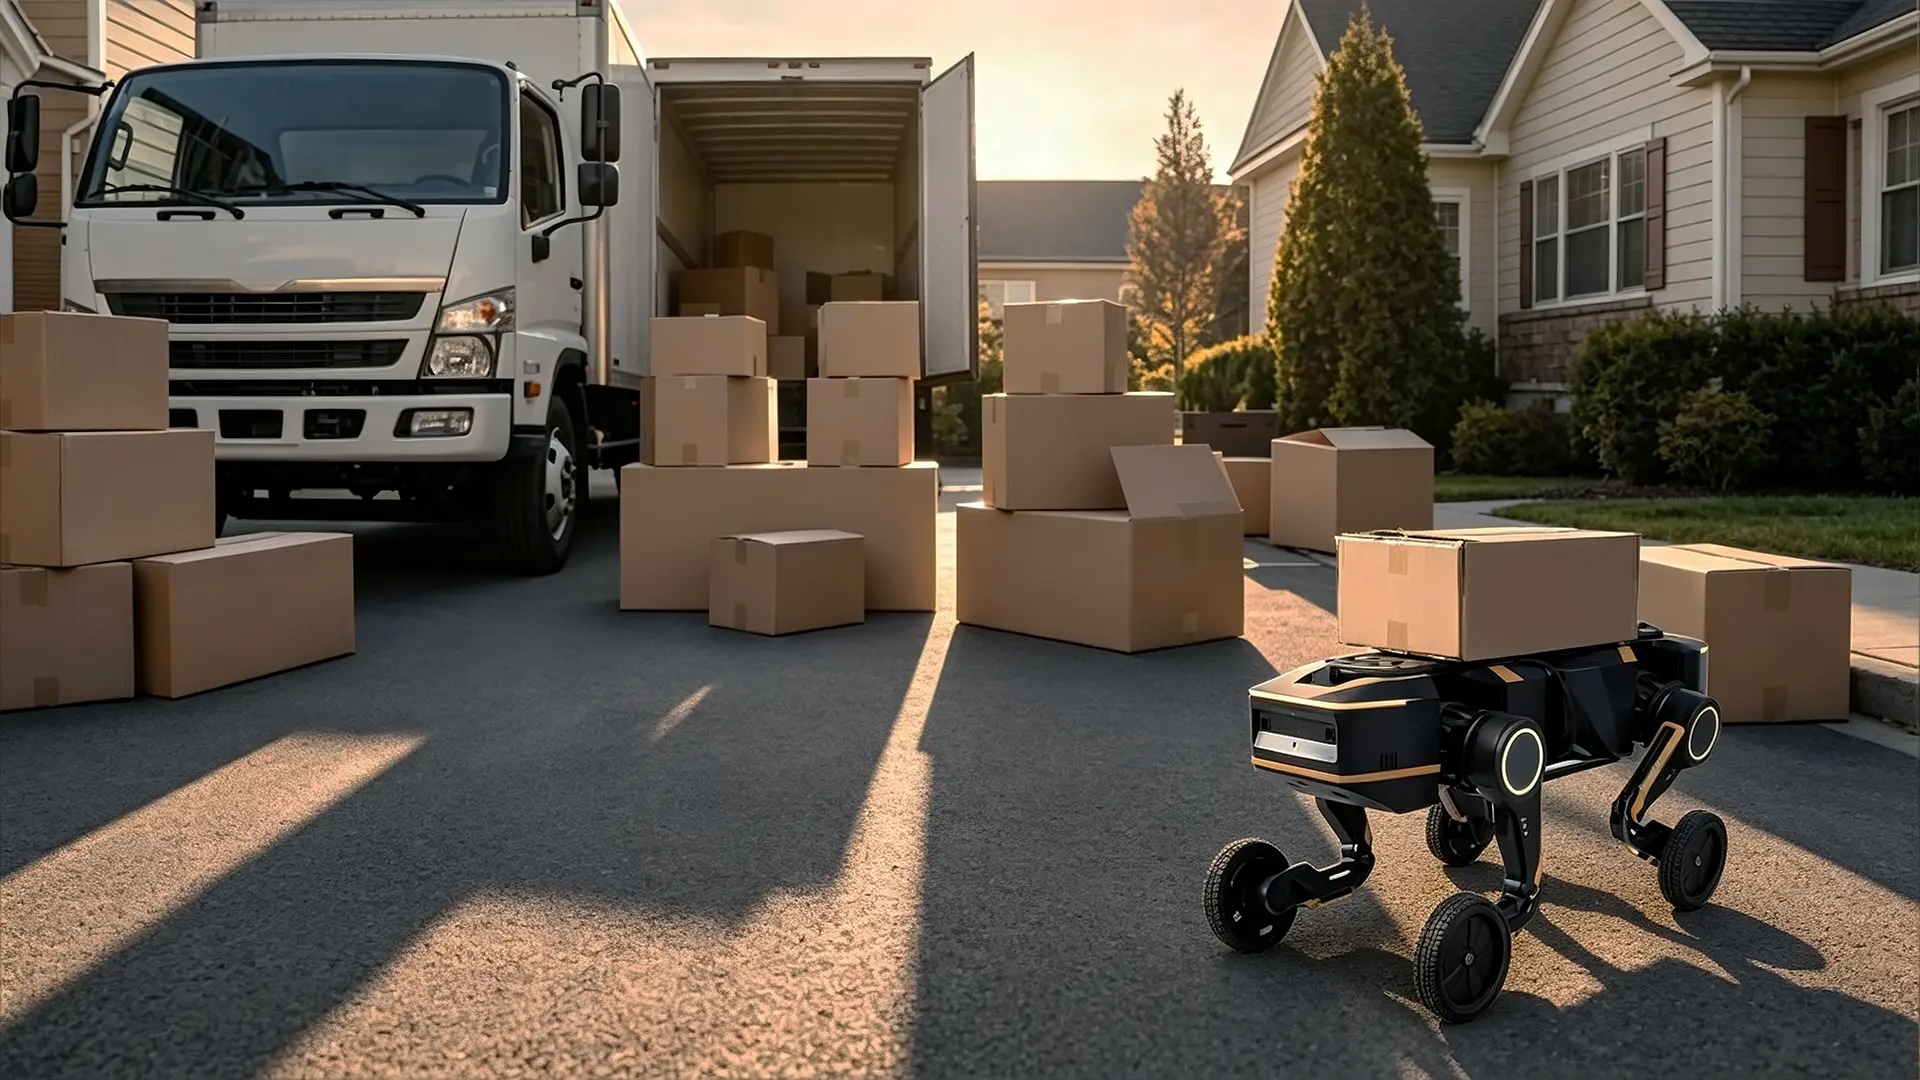
The company is aiming to list in Hong Kong, feasting on a Chinese direct drive actuator module market that soared from 200 million yuan in 2023 to 1.9 billion yuan last year
Key Takeaways:
- Direct Drive Tech has filed for a Hong Kong IPO, reporting its sales rose 40% in the first half of this year after tripling in 2025
- The company controls more than 60% of China’s market for consumer-use direct drive actuator modules that are a key component of affordable household robots
By Doug Young
Humanoid robots look set to become key helpers in homes of the future, assisting with everything from daily chores like cleaning, cooking and laundry, to taking care of the elderly and children. But in the present, a much simpler generation of consumer robots is rapidly gaining traction by performing many similar tasks on much smaller budgets.
One company underpinning this quieter robot revolution is Direct Drive Tech Ltd., a robotics technology company with two business segments, robotic actuator modules and robots, which hopes to impress investors with its rapid growth and fast-improving margins, as it marches towards a planned Hong Kong IPO. The company filed its IPO prospectus with the Hong Kong Stock Exchange last month and added an update on Sept. 17, with Citic Securities (Hong Kong) as its sole sponsor.
The company was last valued at 3.2 billion yuan in its Series C financing at the end of last year, in which it raised 185 million yuan ($27.6 million). Now, it aims to raise another HK$982.5 million ($125 million) in its Hong Kong IPO by selling 50 million H-shares for HK$21.60 apiece, according to its latest listing document filed on Sept. 21.
The company’s core product, the actuator modules that give robots their ability to move, only sell for a few dollars each, reflecting the relative maturity and growing affordability of a fast-growing industry cranking out products for daily activities like household cleaning, lawn care and fitness.
But when you multiply that by the millions, the opportunity is quite large and growing quickly. China’s direct drive actuator module market grew by more than a factor of eight from just 200 million yuan in 2023 to an estimated 1.9 billion yuan last year, according to third-party research in Direct Drive Tech’s prospectus.
The company is hardly the only one chasing that space, competing with global players like Japan’s Harmonic Drive Systems (6324.T), as well as domestic rivals Leaderdrive (688017.SH) and ZhongDa Leader (002896.SZ). But it’s carved out a very comfortable space in the market for consumer-use direct drive actuator models, controlling 61.1% of that market in China last year, according to the prospectus.
Its listing would make Direct Drive Tech Hong Kong’s first “direct drive actuator module” stock. And unlike higher-profile humanoid robot makers and their suppliers, most of which are deeply in the red, Direct Drive Tech, despite its relatively short history, is inching its way towards profitability on an adjusted basis, which excludes share-based compensation and changes in financial instruments.
The company is also distinguished as the only one in its segment to ship more than 5 million consumer-use direct drive actuator modules. It was on track to ship more than double that figure this year, as it sold 5.7 million modules for consumer-use robots in the first half of this year.
That sales ramp-up is a big part of the company’s story. Annual capacity at its two production bases in the city of Dongguan more than quadrupled to about 15.7 million modules last year from about 4.1 million in 2024. It continued to grow this year, on track to reach more than 20 million units annually.
Young company
Direct Drive Tech has made significant strides in short order to get to its current phase, founded just six years ago in Dongguan before moving its headquarters to Beijing last year. Its founder and Chairman, Zhang Di, started his company at age 26 after earning a bachelor’s degree in mechanical engineering from the Beijing Institute of Technology, and then studying robotics systems and control engineering at the Hong Kong University of Science and Technology.
The company’s story is one of rapid scaling and improving business metrics since it rolled out its first actuator modules shortly after its founding in 2020.
Its revenue more than tripled to 282 million yuan last year from 79.8 million yuan in 2024, and grew another 40% to 200 million yuan in the first half of this year from 143 million yuan a year earlier. Consumer-use robotic direct-drive actuator modules are its biggest revenue source, accounting for 82% of its revenue this year.
The company’s industrial and commercial actuator modules business is a much smaller but fast-growing segment, roughly tripling to 21 million yuan in the first half of this year from 6.58 million yuan a year earlier, rising to 10.5% of revenue from 4.6% over that period.
Beyond modules, the company’s second business segment, robots, showcases its direct drive technology at the complete-machine level, despite the segment’s modest share of total revenue. With wheel-legged robot revenue of 7.3 million yuan in 2025, the company ranked fourth in China’s wheel-legged robot market with a 4.7% market share, according to research in its prospectus.
Advances in motor power density and efficiency could also broaden the use of its higher-margin joint modules in humanoid robots and other embodied-intelligence systems, potentially lifting overall gross margins. Joint modules generated a gross margin of 29.2% in the first half, compared with 17.2% for consumer direct-drive modules, although they accounted for just 1.7% of revenue.
Here, we should point out that one of the company’s vulnerabilities is its relatively high customer concentration. Its top five customers currently account for more than 80% of its sales, with its largest accounting for more than half in the first half of this year.
As its scale improves, the company’s gross margin has been improving rapidly, rising from 13.5% in 2023 to 21.5% last year. Its expenses as a percentage of revenue have also been coming down steadily, which is exemplified by its R&D costs, which dropped from 223% of revenue in 2023 to just 19.7% last year. That figure rose to 26.8% of revenue in the first half of this year, as the company cited spending related to its rapid business expansion.
Direct Drive Tech’s adjusted non-IFRS net loss also dropped from 61.2 million yuan in 2023 to 43.2 million last year.
Despite its progress, the company’s 21.5% gross margin last year still trailed peers like Harmonic Drive and ZhongDa Leader, which recorded margins of 30.5% and 26.1% in their latest fiscal years, respectively. But steady improvement with its growing scale could soon help Direct Drive Tech to catch and even surpass those rivals, as it continues to feast on a fast-growing and proven market for simple home-use consumer robots.
The Bamboo Works offers a wide-ranging mix of coverage on U.S.- and Hong Kong-listed Chinese companies, including some sponsored content. For additional queries, including questions on individual articles, please contact us by clicking here
To subscribe to Bamboo Works free weekly newsletter, click here
Related Articles
RELATED ARTICLES
-
Ubtech charms investors with companion robots – until reality sinks in
- The new smart home: Where robots handle chores and provide companionship
- Dobot taps Shenzhen market to fund its bet on humanoid robots
- Specialized embodied robots: A massive next-generation opportunity
- Why humanoid robots are still more about showmanship than productivity
- INTERVIEW: Cainiao rolls out ZeeBot in latest step toward ‘Dark Warehouses’
-
Hesai eyes next big thing with robotics initiatives
HSAI.US2525.HK





