
Gaw Capital builds new foundation on private real estate debt
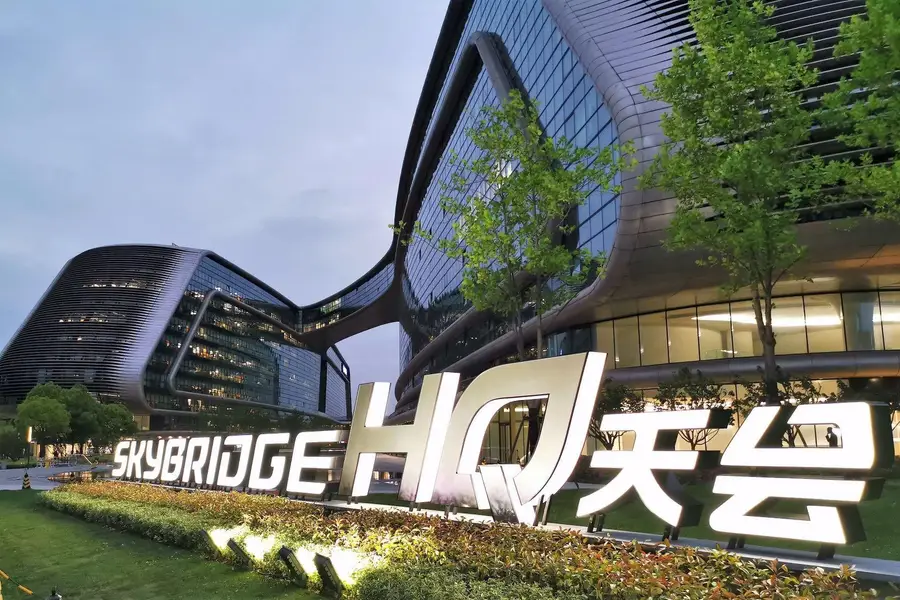
The property investment specialist plans to list Hong Kong’s first real estate private debt fund, in a major financial milestone for the city
Key Takeaways:
- Gaw Capital will set up a private debt fund, with 90% of total assets allocated to real estate
- Assets in the new real estate private debt fund, which would be the city’s first, must be collateralized by actual properties
By Lau Chi Hang
As Chinese developers grapple with a defiantly sluggish real estate market, many are packaging some of their assets and spinning them off as real estate investment trusts (REITs) to generate cash. Struggling former Hong Kong titan New World Development (0017.HK) was the latest to jump on that bandwagon when it outlined plans last month for a REIT underpinned by some of its commercial properties in Shanghai.
Now, Hong Kong’s Gaw Capital is taking a page from the recent REIT craze with a slightly different twist, by applying to list its Gaw Capital Real Estate Private Debt OFC on the city’s stock exchange. With underlying assets consisting of real estate private debt, a listing could set a precedent for alternative funds as Hong Kong tries to retain its place as one of Asia’s premier financial markets.
Debt fund key advantages
Real estate private debt refers to loans made to developers by non-bank institutions through privately negotiated and non-publicly issued arrangements. Funds structured around this type of debt typically distribute the majority of the interest collected to fund holders after deducting operating expenses.
Such funds offer three primary advantages over other dividend-paying products. They typically provide higher yields than traditional bonds and bank deposits. What’s more, their loan agreements often feature floating interest rates, which can boost returns during periods of rising interest rates. And equally important, the debts are collateralized by real estate, providing a solid layer of downside protection in the event of defaults.
The real estate private debt fund Gaw Capital is launching will be managed by Gateway Capital (Hong Kong) Ltd., one of its subsidiaries. Gaw Capital was founded by brothers Goodwin and Kenneth Gaw, whose father, Anthony, founded the Hong Kong-listed Pioneer Global Group. Goodwin established Downtown Properties in the U.S. in 1990, focusing on the revamp and revitalization of distressed buildings.
The two brothers first teamed up in 2005 when Kenneth, the younger of the pair, was working at Goldman Sachs in Hong Kong. They established Gaw Capital, with a primary focus on real estate investment. Their early projects were concentrated in China, including a breakthrough deal with their acquisition of an unfinished project in Shanghai. They later completed the project, which is now the trendy, youth-oriented Plaza 353 on the Nanjing Dong Lu pedestrian street in Shanghai’s busiest shopping area. They later invested in Swire Properties’ Taikoo Li project in Beijing, injecting fresh momentum into the city’s aging Sanlitun district that has since re-emerged as a popular shopping area.
Acquiring subway-linked REIT assets
Back at home, Gaw Capital stunned the market in 2015 when it spearheaded a HK$7.3 billion ($930 million) acquisition of the InterContinental in Hong Kong’s Tsim Sha Tsui district, setting a record for the largest single hotel transaction in the city at the time. The firm later reached the pinnacle of its prominence by spending HK$35 billion to acquire 29 shopping malls from the Link REIT, the property arm tied to Hong Kong’s subway operator.
Between 2021 and 2025, Gaw Capital’s assets under management reached $35.6 billion. Since 2018, the firm has deployed approximately $1.27 billion in real estate private debt transactions across the Asia-Pacific region through its credit fund.
According to the listing application, the Gaw Fund’s investment manager has identified a hypothetical loan portfolio for the new private debt fund. This includes debt linked to commercial and residential properties in Hong Kong; Australian residential developments in the states of Victoria and New South Wales; hotels in Thailand and the Maldives; and a South Korean residential development in Seoul.
Annualized interest rates for the various projects in the portfolio range from 8.8% to 14.5%, with terms spanning from 12 to 24 months.
High returns, high risks
While the interest rates look quite attractive, investors shouldn’t overlook some inherent risks. Should one of the debts default, investors would not only lose out on interest payments, but in severe cases, might even fail to recover some or all of their principal. Such defaults have become increasingly common in the current weak real estate market, where developers or project borrowers find themselves unable to service their debts.
Although the Gaw Fund’s debt is backed by real estate collateral, continued declines in the property market could severely erode asset values, potentially leading to situations where collateral values fall below outstanding debt. In such “upside-down” scenarios, the fund could still face substantial losses, even if it seizes the underlying assets.
It’s also worth noting that some of Gaw Capital’s own real estate projects are facing financial pressure. Late last year, lenders demanded repayment of a $258 million loan tied to Ocean Towers in Shanghai. While Gaw Capital managed to extend the loan maturity to November this year, final resolution of the issue remains uncertain.
Then there’s a HK$10.3 billion syndicated loan tied to Hong Kong’s Cityplaza Three and Cityplaza Four commercial developments, which ran into difficulties after Gaw Capital acquired them for HK$15 billion in 2019. The firm was only able to breathe a temporary sigh of relief after securing the lenders’ consent to extend the loan’s maturity.
Rising interest rates could also pose a challenge to debt funds like the one Gaw Capital is setting up. Yields for bonds issued in Hong Kong this year have already trended on the higher side. As cases in point, a recently issued Silver Bond offered a guaranteed minimum interest rate of 4.25% and was linked to inflation, while Green Bonds issued last month offered yields ranging from 3.8% to 5%.
While the Gaw Fund is expected to distribute higher dividends than those bonds, investors will have to shoulder higher risks. By comparison, bonds issued by the Hong Kong government carry virtually zero default risk, offering both high yields and greater safety. And with U.S. interest rates on the rise, Hong Kong rates are likely to follow suit. As future bond yields potentially climb even higher, the Gaw Fund is bound to lose some of its appeal.
To subscribe to Bamboo Works weekly free newsletter, click here
Related Articles
RELATED ARTICLES
-
New World looks to REIT in bid to rescue its shaky foundation
 0017.HK
- China’s AI advances mask widening gap with U.S. in private capital investment
-
Developer lifeline: Seazen seeks financial relief through REIT spinoff
1030.HK
- With looming debt pressures, Agile faces tough road to restructuring
-
Qfin gets frostbite as fintech winter intensifies
QFIN.US
-
Bleeding cash and mired in debt, Haichang teeters on the brink of collapse
2255.HK
- Its losses widening, Bitfire builds up its bets on the stablecoin race





