
CIG redirects $225 million of IPO funds to massive optical business buildup
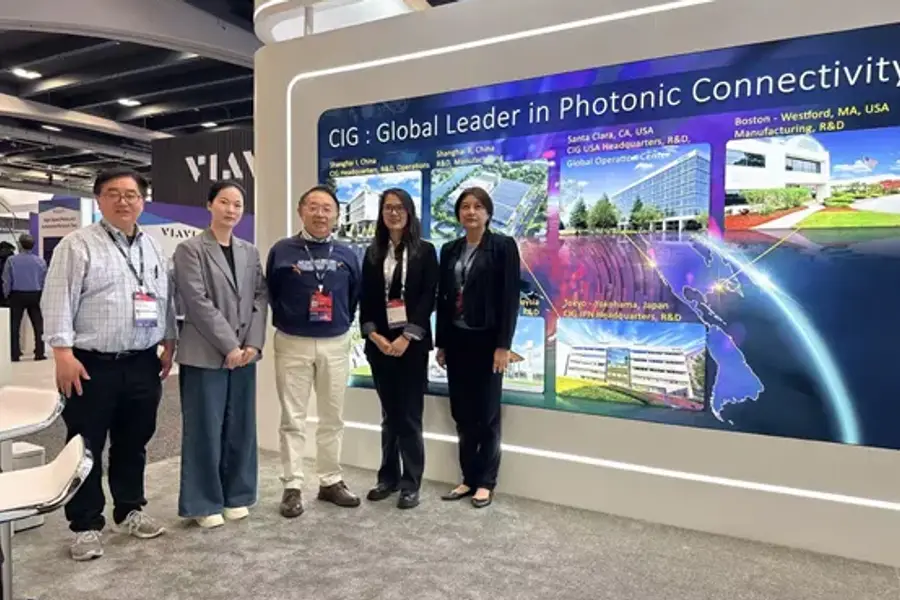
The company is pouring roughly HK$5 billion in fresh funds into its optical transceiver unit whose sales are soaring on the global AI infrastructure buildup
Key Takeaways:
- CIG will redirect HK$1.77 billion of its IPO funds originally earmarked for its legacy broadband and wireless businesses into its newer optical products unit
- The company’s revenue rose 67% in the third quarter, double the rate in the first half, on exploding demand from AI infrastructure and cloud computing customers
By Doug Young
It’s not difficult to see why CIG Shanghai Co. Ltd. (6166.HK; 603083.SH) is suddenly going all out on its business making optical transceivers for use in cloud computing and AI data centers. That part of its business has posted explosive growth over the last two years, and this year passed its older wireless and broadband products to account for more than half of its revenue.
Still, you have to wonder if the company might be betting too heavily on this sudden golden goose. The company announced its first big new bet on the optical transceivers business last month by raising about HK$6.54 billion ($834 million) through a concurrent new share placement and convertible bond issue. And last Friday, it announced it will redirect another HK$1.77 billion it raised in its Hong Kong IPO last year to its optical transceiver business from earlier plans to spend the money on its wireless and broadband businesses.
All this is happening as CIG reported on Friday that its revenue growth accelerated to 67% in the third quarter, reaching 2.22 billion yuan ($333 million) for the period. That was double the 33% growth the company recorded in the first half of the year. CIG’s profit was even better, rising 213% to 433 million yuan in the third quarter, faster than the 171% rise it reported in the first half of the year.
The catalyst behind the company’s sudden growth spurt is the concurrent build-out of cloud computing and AI data centers. The company’s optical transceivers are an important piece of that infrastructure, facilitating the high-speed signal transmission that is needed for cloud computing and especially AI applications.
Goldman Sachs forecasts the global market for optical modules will grow from $51 billion this year to $73 billion in 2027, before falling slightly to $69 billion in 2028. But the market for 500G and faster transceivers, which is a subset of that market and is CIG’s specialty, is expected to grow throughout the period from $32 billion this year to $55 billion in 2027, and then rise modestly to $56 billion the year after that.
But all those rosy forecasts could suddenly get voided if the AI spending bubble bursts, which looks increasingly likely as many point out that revenue from AI services is far smaller than spending on product R&D and infrastructure building. If that happens, CIG could suddenly find itself with huge amounts of newly constructed but underutilized capacity. And it’s hardly the only company building up such new capacity, with most of its rivals taking similar steps.
And while CIG is shrewdly funding much of the buildup by issuing new shares, it’s also taking on significant new debt through the convertible bond issue. The HK$4.6 billion in convertible bonds it issued last month are quite short-term, coming due in just a year. It won’t cost CIG anything if the bondholders chose to convert their notes to shares at a conversion price of HK$128.82 per share.
But CIG’s shares have lost about half their value since late September, and closed at just HK$63 last Friday. That means that unless the shares stage a major rally over the next year, the convertible noteholders could simply ask for repayment of their principle when the notes come due next year. If that happens, CIG might have to suddenly cough up nearly $600 million that it might not have if it keeps up its rapid spending on building new optical transceiver capacity.
Fundraising frenzy
CIG has been on a fundraising frenzy over the past year, initially with plans to build up its three core businesses in broadband, wireless and optical products. It raised about HK$5.16 billion in its Hong Kong IPO about a year ago, complementing its existing domestic listing in Shanghai. Its bond and new share issues last month bring its total fundraising over the last year to about $1.5 billion.
In its disclosure last week, the company said it has spent very little of the HK$1.3 billion from its IPO proceeds originally earmarked for expanding and developing its wireless and broadband businesses. By comparison, it has spent all of the roughly HK$1.3 billion earmarked for the optical products business.
Given the optical products business’ better prospects, the company said it now plans to redirect HK$1.77 billion of its IPO funds from their originally intended use in its broadband, wireless and other areas into its optical business. That’s on top of roughly HK$3.27 billion from last month’s bond and share sales that will also go into the optical business.
As we noted at the outset, it’s not difficult to see why CIG is plowing so much money into its optical business. The company hasn’t given any breakdown of revenue contributions from its three main product categories this year, though it noted its broadband and wireless product sales both fell in the first half of the year. And last year, the company’s optical revenue rose 240%, while its broadband fell 2% and its wireless rose 2.5%.
What’s more, the optical products business is far more profitable, commanding a gross margin of 34.5% last year, compared with 14% and 19% for broadband and wireless products, respectively.
As demand for optical transceivers grows, CIG is also expanding its global customer base. It pointed out it has made significant recent inroads in the important North American market, benefiting from infrastructure builders seeking to diversify their supplier bases.
Shareholders seem to be growing increasingly cautious on aggressive expansion plans by CIG and its peers, as reflected by the sharp declines in their stocks since September. While CIG is down by about half since then, Zhongji Innolight’s (3308.HK; 300308.SZ) Hong Kong shares are down 36% over the past month, while Eoptolink Technology (300502.SZ) is down 47%.
Even after the selloff, CIG’s Hong Kong-listed stock still trades at a relatively high trailing price-to-earnings (P/E) multiple of about 40. But that’s likely to drop to around 25 based on its strong profit growth this year. That would be roughly in line with the P/E ratio of 26 for Innolight, and 19 for Eoptolink. But the real danger for all these companies is if AI infrastructure spending slows sharply, which would leave them all with large amounts of unused capacity and billions of dollars in debt they might have trouble repaying.
To subscribe to Bamboo Works free weekly newsletter, click here
Related Articles
RELATED ARTICLES
-
Dongshan Precision targets AI optics with Hong Kong listing
 2384.HK002384.SHE
-
InnoLight shines on AI infrastructure spending binge
3308.HK300308.SHE
-
Optical communications leader Eoptolink plans Hong Kong listing
300502.SHE
- FS.com rides high-speed AI networks to higher profits
- SpaceSail seeks billions for China’s Starlink challenge, as revenue remains earthbound
- Volant fuels up for Hong Kong IPO with $450 million in new funds
- Cowell remains tethered to Apple. But you could do worse



