Haitian finds bitter taste in China’s restaurant slowdown
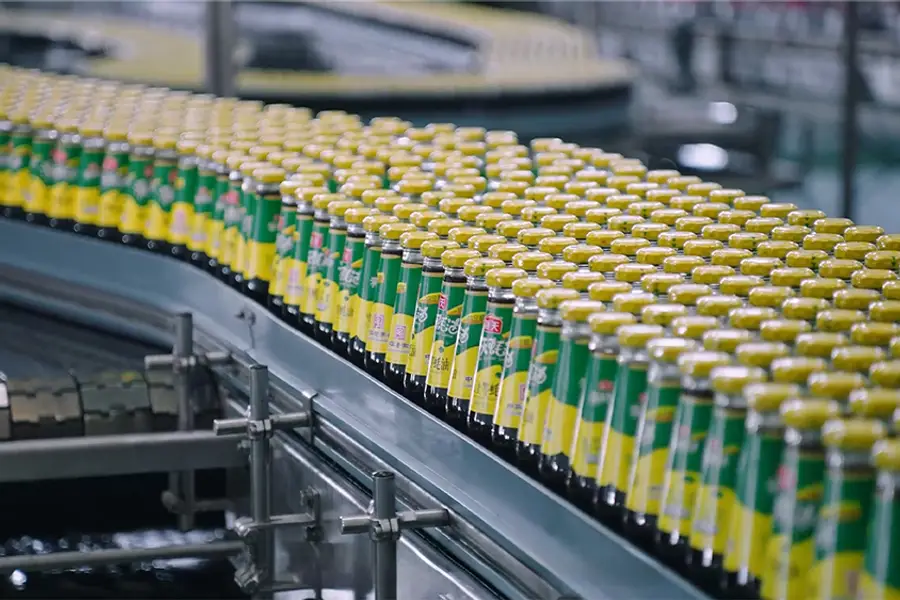
The country’s leading soy sauce maker’s revenue flattened in the third quarter, as sales for its core product contracted year-on-year
Key Takeaways:
- Haitian reported its revenue was flat in the third quarter, as sales of its key soy and oyster sauces both contracted
- The leading soy sauce maker is falling victim to China’s restaurant slowdown, since more than half of its sales come from the catering industry
By Doug Young
China’s economic slowdown should theoretically benefit consumer staples makers like Foshan Haitian Flavouring and Food Co. Ltd. (3288.HK; 603288.SH), China’s largest soy sauce maker with more than 300 years of history dating back to the Qing Dynasty. After all, everyone needs to eat, and many more people are doing that at home these days to save money in an increasingly uncertain economy. And soy sauce is China’s leading condiment, meaning sales should be growing.
But sales are slowing to almost zero for Haitian, whose latest quarterly report, released on Thursday, shows its revenue was basically flat in the third quarter, rising just 0.1% to 6.41 billion yuan ($962 million) from 6.4 billion yuan a year earlier. The latest figure continues a trend that’s been building during the year, as the company’s revenue growth slowed from 8.6% in the first quarter to about 3% in the second.
All this comes as China’s food sales continue to post healthy growth. Grain, oil and food retail sales were up between 4% and 7% in each of the three months during the third quarter, according to government data, partly reflecting the trend towards more dining at home.
Instead, the culprit undermining Haitian’s business appears to be China’s restaurant industry, which is being hurt by the increase in dining at home. Haitian doesn’t break down its sales to consumers versus restaurants in its financial reports. But a February 2025 report from Dongguan Securities estimated around 60% of the company’s sales go to restaurants.
And unlike retail food sales, restaurant sales haven’t been doing nearly so well these days. Government statistics show that revenue from China’s catering industry rose between just 1% and 2% in July, August and September, slowing sharply from 4.2% in the first quarter of this year. Making matters worse, recent trends have shown that big chains that are probably some of Haitian’s biggest customers are faring worse than the industry average, as more consumers flock to independent outlets that can offer lower prices by buying cheaper ingredients and spending far less on marketing.
All that bodes poorly for Haitian going forward. Analysts currently expect the company’s revenue to rise 6.8% this year, according to 18 polled by Yahoo Finance. But based on the company’s 4.3% growth in the first nine months of the year, we expect that many of those analysts may soon revise down their forecasts.
Analysts are generally positive on the company, with eight of 10 surveyed by Yahoo Finance rating the company a “buy” or “strong buy.” But some of those might also be rethinking their rating if the company slips into revenue contraction in the fourth quarter, which looks like a strong possibility if current trends continue.
Despite the glum news, Haitian’s Hong Kong-listed stock was relatively steady on Friday after the release of the latest quarterly report, with the shares roughly unchanged in late morning trading. But the stock is down about 30% since it listed in Hong Kong in June 2025, tracking a broader trend that has seen many restaurant shares sag over that time.
Lowly valued
Haitian’s poor post-IPO performance has left its Hong Kong-listed shares trading at a price-to-earnings (P/E) ratio of just 7.7 times, well behind the 12 for frozen prepared foods maker Anjoy (2648.HK; 603345.SH), though slightly ahead of the 6.4 for Guoquan (2517.HK), a maker of hotpot seasonings for at-home dining.
The low figures reflect the slow growth outlook for this broader food category. Restaurant sales were probably a bright spot for this group during better economic times when people ate out more frequently. But those days are disappearing in the current climate, meaning the stocks could come under more pressure. Shares of Anjoy are down about 30% over the last half year, while Guoquan is down by an even steeper 65%.
A look at Haitian’s major food categories shows its core soy sauce is faring particularly poorly. Soy sauce sales, which account for about 54% of the company’s revenue, grew just 2.8% year-on-year in the first nine months of the year, slowing sharply from 4.6% growth in the first half. And some calculations using both data points shows the company’s soy sauce sales actually started contracting in the third quarter, falling 1.7% year-on-year to 3.17 billion yuan from 3.23 billion yuan a year earlier.
Oyster sauce, the company’s second largest category, making up about 18% of its revenues, rose just 0.2% in the first nine months of the year, slowing from 2.6% growth in the first half. Similar calculations using those two points show revenue from that category also dropped by 5.1% year-on-year in the third quarter.
The company’s flavored sauces category, its third biggest income source at 11% of revenues, also grew just 1.4% in the first nine months of the year, though that was a slight improvement from 1.2% growth in the first half. Its lone bright spot was its specialty condiments and others category, which was up 10.7% in first three quarters of the year. But even that marked a slowdown from a 13.5% rise in the first half.
Like many of its peers, Haitian is trying to boost its sales by catering to a younger generation of consumers looking for more convenient products like pre-mixed seasonings, as well as healthier condiments. In its mid-year report, the company pointed out it is trying to cater to those health-conscious younger consumers with products like reduced-salt and organic soy sauces, as well as sugar and gluten-free products.
That element shows up in its R&D costs, which rose 16% in the first three quarters of the year, though is still quite low at just 3.3% of revenues.
At the same time, the company’s balance sheet shows a few worrisome trends. Most notably, its trade receivables rose nearly 50% to 439 million yuan by the end of September from 236 million yuan at the end of last year, indicating a growing number of its customers, many of them probably restaurants, are having difficulty paying their bills. None of that bodes well for the company, as it looks likely to slip into overall revenue contraction by the end of the year.
To subscribe to Bamboo Works weekly free newsletter, click here
Related Articles
Hisense catches chill from cooling Chinese economy
Senior Material’s quarterly profit surges, but investors unimpressed
RELATED ARTICLES
-
Juhui rides domestic catering boom to Hong Kong IPO
-
Xiaocaiyuan shuns takeout delivery for in-restaurant dining
0999.HK
- Slowing takeout dining wars leave Luckin with bitter aftertaste
-
JBM Healthcare gets bitter pill from investors on anemic performance
2161.HK
- BRIEF: Yum China not included in second bidding round for Jardine Restaurant Group
- GreenTree revenue falls on weakness in hotel, restaurant businesses
-
Hisense catches chill from cooling Chinese economy
0921.HK000921.SHE