The company’s third-quarter revenue plunged between 45% and 50%, led by drops of more than 65% in its Asia Pacific and Americas markets
Key Takeaways:
- Pop Mart’s third-quarter revenue fell up to 50%, as sales outside its home China market dropped dramatically with the fading of last year’s Labubu craze
- The toy maker’s stock has lost two-thirds of its value from an all-time high last year, leaving it valued lower than domestic and global peers like Bloks and Hasbro
By Doug Young
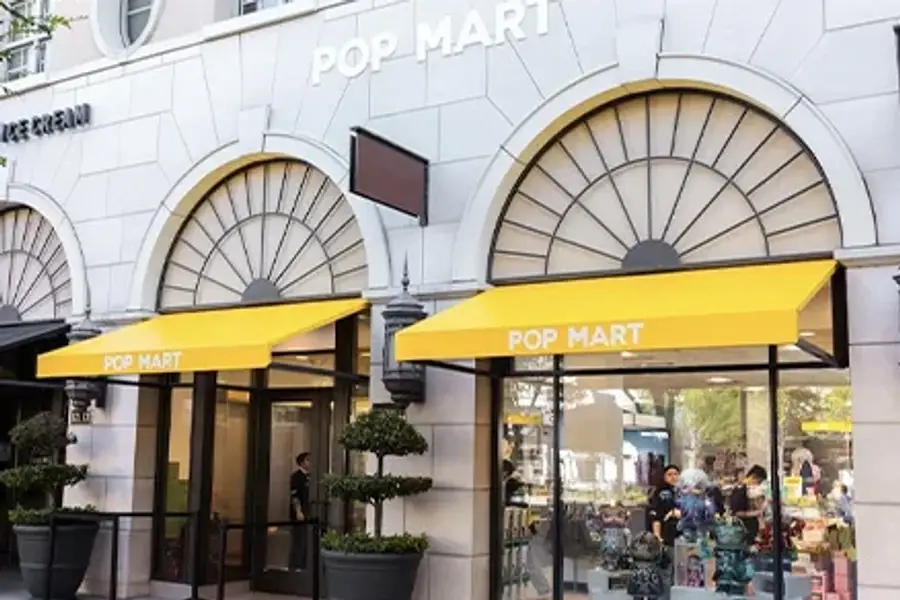
It became a global sensation last year as a wide range of collectors, from tweens to young adults, snapped up its Labubu-themed toys worldwide. But these days, Pop Mart International Group Ltd. (9992.HK) is living up to its own name, with the “popping” of the company’s bubble as its Labubu sales crash almost as spectacularly as they rose.
In fact, we don’t really know if Labubu’s rapid fading is the culprit behind a major plunge in Pop Mart’s third-quarter revenue, which it revealed in a business update on Tuesday after markets closed. But many are probably guessing Labubu is mostly to blamed for a 45% to 50% year-on-year drop in Pop Mart’s revenue in the third quarter, according to the announcement.
Pop Mart didn’t provide any reason for the spectacular fall, though it did give additional details that show it took the biggest hit outside its home China market. That isn’t too surprising, since the company’s toys were virtually unknown outside China before the Labubu craze. So, it stands to reason that Pop Mart would return to its status as a China-centric company once that fad ran its course.
While the size of its decline was quite spectacular, investors seemed to take the news with a certain degree of serenity. Pop Mart’s stock was down by a relatively mild 0.7% in mid-morning trading on Wednesday, the day after the announcement. But at their current price around HK$130, the shares have lost about two-thirds of their value from a peak of around HK$340 in August last year at the height of the Labubu craze.
That craze was fueled in no small part by a string of celebrities seen carrying the furry toy known for its toothy smile. One of the earliest to take a shine to Labubu was Lisa of Korean pop group Blackpink. Others later seen with the toy ranged from U.S. pop star Rihanna to influencer Kim Kardashian and British soccer legend David Beckham, testifying to just how wide the toy’s appeal ranged.
Such sightings not only boosted sales, but also led to huge lines of adoring fans waiting to buy the toys at Pop Mart’s signature stores and other outlets. They also created a huge aftermarket for the toys, which often sold for well above their official retail prices.
Labubu was still riding high as recently as the first half of this year, when it was prominently featured at the FIFA World Cup soccer tournament. In its report for the first-half of 2026, Pop Mart pointed out the character was featured in a track on the tournament’s official album. Labubu was also a guest at both the opening and closing ceremonies, becoming the first original Chinese IP to achieve that distinction.
But as the saying goes, all good things must end, which is what is happening now with the Labubu craze. That said, Pop Mart has a relatively strong cast of other popular characters in its portfolio, which might explain why initial investor reaction to the latest business update was relatively muted.
International plunge
Next, we’ll take a closer look at the details from the latest announcement, which show how Pop Mart took an especially hard beating outside China.
The company took the biggest hit in America, where its third-quarter sales fell between 70% and 75% year-on-year. That’s not too surprising, since the company’s Americas sales had previously posted explosive growth, rising by more than 1,000% in the first half of last year to 2.26 billion yuan ($339 million), growing to 16.3% of the company’s total revenue from just 4% a year earlier. The company’s Asia Pacific sales also fell by an almost-as-bad 65% to 70% in this year’s third quarter, while its sales for Europe and other regions tumbled 50% to 55%
China outperformed those global markets, though sales on Pop Mart’s home turf were also down between 25% and 30%. Within China, offline sales from the company’s network of brick-and-mortar stores and vending machines fell between 5% and 10%, while online sales were down by a larger 45% to 50%.
As we’ve already noted, Pop Mart didn’t give any explanations for the sharp declines. We should also note that the big drop was also at least partly due to a difficult comparison from a year ago at the height of the Labubu craze, when the company reported its sales rose 250% in the third quarter of 2025 from the same period a year earlier.
That said, the latest sharp decline comes as a slight surprise because Pop Mart was still posting healthy revenue gains in the first half of this year. Its revenue in the six months to June rose 23.8% to 17.2 billion yuan, as its Monsters series, which includes Labubu, brought in 4.45 billion yuan, or about a quarter of sales. Here, we should point out the Monsters were already fading in the first half of this year, falling to 26% of the company’s total revenue from 38% in all of 2025.
The sharp third-quarter reversal bodes poorly for Pop Mart, since the second half of each year typically accounts for about two-thirds of the company’s annual sales. Reflecting that, the average of 21 analysts polled by Yahoo Finance expect the company’s revenue for all of this year to fall 5.4%. Those analysts are also quite mixed on the company, split around 50-50 between ones recommending the shares and ones rating it a “hold” or lower.
The good news is that Pop Mart is relatively diversified in terms of revenue from its different product lines. While the Monsters line that includes Labubu is its biggest revenue source, its Twinkle Twinkle, Crybaby, Dimoo, Skull Panda and Hirono lines all generated revenue of 1 billion yuan or more in the first half of the year.
The company is also still quite profitable, reporting its profit rose 10% to 5.04 billion yuan year-on-year in the first half of 2026 on a very attractive gross margin of nearly 70%. What’s more, its stock is also looking far more attractive now after the recent selloff, trading at a price-to-earnings (P/E) ratio of just 12 times trailing earnings. That’s well below the level of about 18 for domestic rival Bloks (0325.HK) and global giant Hasbro (HAS.US), showing that Pop Mart may present an attractive buying opportunity as its situation stabilizes in the post-Labubu era.
To subscribe to Bamboo Works free weekly newsletter, click here
Related Articles
Hisense catches chill from cooling Chinese economy
Senior Material’s quarterly profit surges, but investors unimpressed
RELATED ARTICLES
-
Miniso gets AI investment lift, as self-developed toys look for traction
 9896.HKMNSO.US
- Pop Mart’s second-half growth target looks difficult, sparking share selloff
-
After nine lost years, China Literature opens new chapter with AI-IP combo
0772.HK
- Xtep races ahead on Southeast Asia running craze
- From pop concerts to plush toys, Damai expands its ecosystem
- Budget air con giant catches chill from tepid home economy, Middle East war
- Chinese ‘Easter Eggs’ fall back to earth after wild year on Wall Street