
Got change? Lexin’s penny-stock plunge reflects sinking fortunes for China fintechs
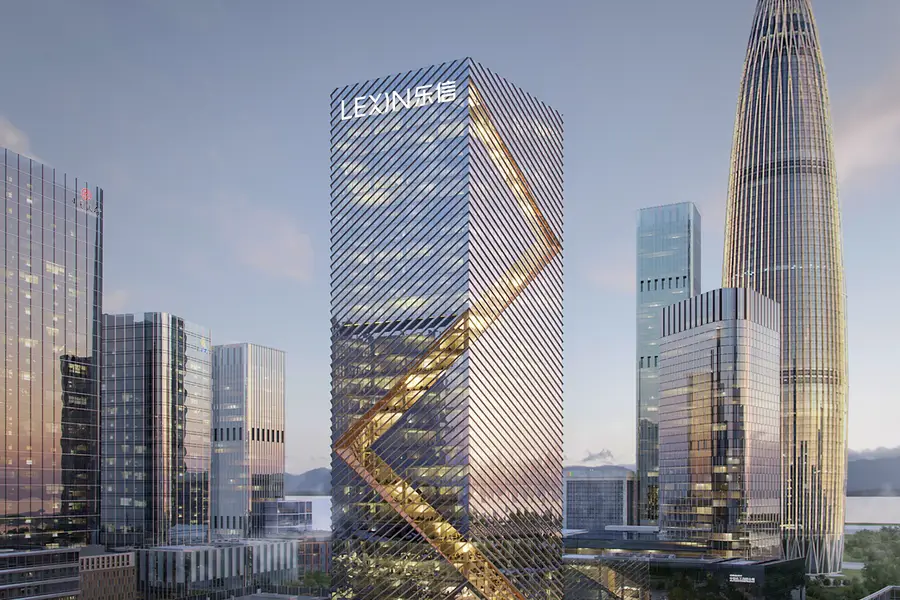
The online loan facilitator faces a potential delisting after its American depositary shares traded below $1 for 30 consecutive business days
Key Takeaways:
- Lexin’s American depositary shares could be delisted from the Nasdaq after trading below $1 for 30 consecutive trading days
- The company’s woes reflect a broader reckoning for a sector reeling from a sudden liquidity squeeze following a high-profile scandal
By Warren Yang
Not too long ago, Chinese online lending companies were investor darlings, boasting a high-margin business model supplying small loans to millions of credit-hungry consumers and businesses. Today, they are fighting for survival.
The latest casualty in the headlines is LexinFintech Holdings Ltd. (LX.US), which last Friday said it received a non-compliance notice from Nasdaq after its American depositary shares (ADS) traded below $1 for 30 consecutive business days.
The company now has 180 days to lift its share price above the unflattering $1 mark, below which it is considered a “penny stock” typically shunned by more serious investors. Failure to do that would lead Nasdaq to issue a formal delisting notice, though Lexin can appeal or apply for a second 180-day grace period. If all that fails, its stock will be formally delisted and move to over-the-counter (OTC) trading.
Lexin is facing these consequences after its shares lost 80% of their value this year alone, dropping them to an all-time low as its market cap fell to the symbolically significant $100 million level. Its ongoing woes are not an isolated case, but instead are symptomatic of a broader reckoning across a sector that’s reeling from a sudden liquidity squeeze following a high-profile scandal. Even before that, Lexin and its peers were having difficulty doing business in a weak economy with ever-tightening regulatory scrutiny to protect the financial system from reckless lending.
The latest drama to rattle the online lending community involves Yiren Digital (YRD.US) and parent CreditEase, whose founder Ning Tang was recently detained by police following redemption freezes and payout delays for the latter’s wealth management products. Those products are essentially off-balance-sheet credit instruments designed to channel investor money to high-risk borrowers like real estate developers outside the heavily regulated formal banking system.
Yiren Digital has said its operations aren’t affected by the problematic wealth manage products, though Tang Ning is the company’s chairman and CEO. And investors have punished the stock anyhow by shaving off 80% of its value this year, also pushing it into penny territory.
This case is significant as CreditEase was once considered a pioneer in peer-to-peer (P2P) lending in China, enjoying the spotlight as the sector rapidly rose to a peak midway through 2010s. The company’s fall from grace underscores how quickly missteps can overwhelm even major players.
As Chinese authorities systematically dismantled the P2P lending industry over the past decade, platform operators were forced to transform into loan facilitators and providers of wealth management products. But while their business models have shifted, underlying credit risks have remained, as the CreditEase episode clearly shows.
CreditEase’s troubles have sent shockwaves through the sector, prompting institutional funding partners to abruptly restrict their supply of loans to online platforms like Lexin. Reflecting this stress, Lexin’s total revenue fell about 11% year-on-year to 3.19 billion yuan ($477 million) in the second quarter as its loan origination volume shrank. Its net profit plunged nearly 80% to 101 million yuan as its provisions against loan losses jumped, with its 90-day delinquency rate shooting up to 3.6% at the end of June from 3.1% a year earlier.
Worse yet, management warned that the company would report a net loss in the third quarter as loan volumes continued to decrease. As financial pressure mounts, Lexin has halted share buybacks and resorted to workforce cuts to conserve cash.
Liquidity shock
The liquidity shock is also hitting Lexin’s competitors. Among them, Qfin Holdings’ (QFIN.US) net profit shrank 77% year-on-year in the second quarter as its revenue dropped by almost a third.
Even before the extraordinary CreditEase saga, it was becoming increasingly difficult for consumer credit companies to grow their business in China as the country’s economy remains sluggish and authorities roll out policies that favor state-owned banks.
So Lexin has expanded into Indonesia, Thailand and the Philippines, offering localized buy-now-pay-later (BNPL) services and consumer credit products — a familiar playbook for Chinese companies moving overseas in search of growth. For Lexin and its peers, Southeast Asia offers attractive demographics characterized by young and digitally native populations and significant underbanked consumers reminiscent of China a decade ago.
FinVolution (FINV.US) is already reaping substantial benefits from international expansion. Its overseas revenue, primarily from Indonesia, the Philippines and Australia, increased about 18% year-on-year in the second quarter to account for 27% of its revenue, up from 22% a year earlier.
However, going global presents operational challenges. For starters, Lexin and its peers need to build relationships with local banks, while data on consumer creditworthiness varies from market to market in terms of quality and availability, making risk management more difficult. Regulations also differ, and well-established incumbents are unlikely to yield their turf without a fight. All this means a plug-and-play transfer of their domestic business model isn’t quite viable. Lexin embarked on its overseas journey several years ago, but its international revenue is still negligible.
As things stand now, turning around its fortunes and winning back investors to its stock in six months to regain regulatory compliance seem like a tall order for Lexin. As a last resort, it could boost its stock price through a reverse share split, which is common for companies in this situation. But Nasdaq is closing loopholes around this popular maneuver among chronic penny-stock companies. Under a rule that took effect at the start of last year, if a company’s stock drops back below $1 within 12 months of a reverse share split, the company no longer enjoys a second 180-day grace period and faces an immediate delisting.
To avoid falling into this delisting trap, Lexin could execute an aggressive reverse split, such as 20-for-1 or 30-for-1, simply to vault its share price comfortably into double digits. Yet this kind of engineering wouldn’t ease pressure on the company’s shares as long as its operational challenges linger.
If the liquidity squeeze continues for online loan facilitators, the real question may be which of them will follow in the footsteps of Lexin into penny stock territory, rather than whether the company will regain compliance and stay listed. Among others, Qfin and FinVolution currently command higher stock prices, trading price-to-earnings (P/E) ratios that are better than Lexin’s 1.6. But even their stock prices aren’t that far from the $1 mark, meaning they could also receive their own non-compliance notices if their shares continue to fall.
To subscribe to Bamboo Works weekly free newsletter, click here
Related Articles
RELATED ARTICLES
-
Yiren Digital left in the cold after parent freezes $4.4 billion in wealth products
 YRD.US
-
Qfin gets frostbite as fintech winter intensifies
QFIN.US
-
FinVolution finds balance with prudence at home, growth abroad
FINV.US
-
BRIEF: Chairman Tang Ning boosts indirect stake in Yiren Digital
YRD.US
- Pomdoctor lands in crosshairs of Nasdaq’s ‘pump and dump’ cleanup
-
Yiren Digital names acting head after chairman falls under criminal investigation
YRD.US
- Lufax reshuffles board as delisting clock ticks down




