OPay rings up Nigeria digital payment prowess for Wall Street investors
The Singapore-based digital payment company has filed to list in New York, offering strong profits from its digital payment services in Nigeria
Key Takeaways:
- OPay has filed for an IPO in the US after building a leading digital payment service in Nigeria targeting people with difficulty using banks
- The Singaporean company’s strategy sets it apart from regional peers that typically look to crowded Southeast Asian markets for geographic expansion
By Warren Yang
An Asian fintech with Chinese ties and a profitable African stronghold is rare enough to command attention. And that’s just what OPay Ltd. has to offer, as it pitches itself to U.S. investors with a sizable new IPO application.
When Asian companies, especially those with China connections, look across their borders for growth, they often follow a well-trodden path into Southeast Asia. With shared trade corridors, massive Chinese diaspora populations, and burgeoning digital economies in Indonesia, Vietnam, and Thailand, these advantages, combined with regional proximity, usually dictate expansion strategies.
Since its foundation, OPay has defied that geographic playbook. And that makes the company a unique — and perhaps compelling — proposition for investors as it seeks a New York listing that media reports say could raise up to $500 million.
The Singapore-based digital payment company, which made its first public IPO filing in the U.S. last week, has skipped past the crowded backyards of Southeast Asia to conquer a far-flung market in Africa. For investors sizing up OPay’s prospects, its central thesis isn’t just another emerging-market fintech play: it is a bolder bet on distant, underbanked frontiers that are currently a decade or two behind markets like China and Southeast Asia.
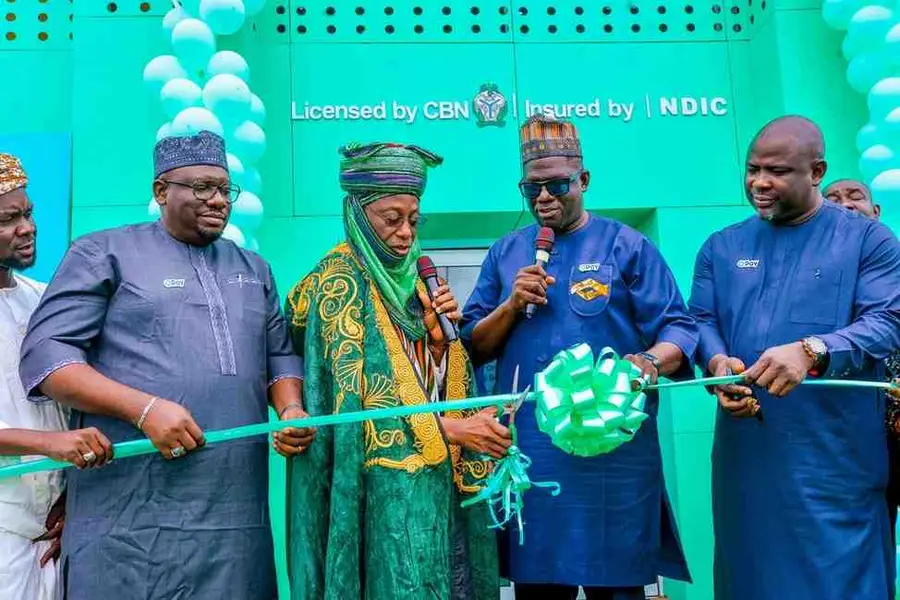
This strategy has paid off handsomely. OPay has become a major fintech player in Nigeria, Africa’s most populous country, with its app ranking as the second most used digital financial platform across all categories in terms of daily active users as of July 2026. Nigeria now accounts for nearly 90% of OPay’s total revenue, with the rest from Egypt, Pakistan and Indonesia.
For OPay, Southeast Asia seems like a natural first stop for geographic expansion beyond its home base in Singapore. But that’s the case for many others, which has turned the region into a crowded, capital-intensive battlefield.
OPay’s unique geographic focus stems from its foundation. It traces its roots to 2017 when Norwegian web browser company Opera — under the leadership of Chinese billionaire entrepreneur Zhou Yahui, founder of Kunlun Tech — acquired PayCom Nigeria before rebranding and launching OPay in 2018.
Instead of pivoting to Southeast Asia, OPay opted to capitalize on Opera’s pre-existing, massive mobile browser footprint in Africa, where legacy banking infrastructure was sparse and many financial transactions were still conducted in cash. OPay pursued an aggressive, multi-service super-app strategy in Nigeria, spanning bike-hailing, food delivery, and micro-lending, in addition to mobile payments. However, regulatory hurdles, including a 2020 ban on commercial motorcycle taxis, and other operational realities forced OPay to dismantle its transport and delivery-related business to focus exclusively on financial services.
By redirecting its resources into physical payment networks and peer-to-peer transfers, OPay became West Africa’s leading financial services gateway, laying the foundation for its expansion into other frontier markets like Egypt and Pakistan.
OPay’s well-established market position in Nigeria is translating into financial gains. The company’s revenue more than doubled to $536.3 million last year, fueled by a 115% surge in its gross transaction value, according to its prospectus. That momentum continued into the first half of 2026, when its revenue already totaled $467 million, up 137% year-on-year and more than 80% of the sum for all of 2025.
Agent banking
Crucially, OPay has translated its hyper-growth into bottom-line profitability. After posting a net loss of $51 million in 2024, it swung to a net profit of $72.5 million in 2025. And its net profit in the first half of this year exceeded $90 million, more than quadruple its $21.7 million profit in the year-ago period.
The company achieved this by aggressively expanding its “agent banking” network. In cash-dominant countries like Nigeria, where traditional bank branches and ATMs are often miles away and plagued by long lines or frequent outages, agent banking acts as an alternate network of mini-bank branches.
Instead of building expensive brick-and-mortar buildings, fintech companies equip everyday local shopkeepers, corner kiosk owners and pharmacy operators with portable point-of-sale (POS) card terminals. These local vendors, known as “agents,” essentially act as human ATMs: customers simply hand cash to agents to instantly deposit digital money into their phone wallets, or transfers digital funds to agents’ accounts to receive cash from the till.
By turning easily accessible local shops into cash-in/cash-out hubs, this model solves the critical last-mile problem of converting physical paper money into digital funds. That allows millions of citizens with little or no access to traditional banks to participate in the online economy without use of actual banks and ATMs.
OPay’s active POS terminal network, including both ATM-like kiosks and merchant payment terminals, grew about 43% to 800,000 machines by the end of June 2026 from the end of 2024.
OPay monetizes its agent banking infrastructure through fees that turn physical cash movements into recurring revenue. The agent network is a relatively low-margin operation, giving OPay a gross profit margin of 20% to 25%. That level isn’t horrendous, but it isn’t great either.
The real value of the agent banking model is that it provides OPay with a huge pool of customers who may use the company’s higher-margin products like loans. Revenue from self-originated loans and loan facilitation fees from partner banks, which carry gross profit margins of more than 70%, make up about half of the company’s revenue.
Despite its African story, OPay’s corporate DNA is undeniably Chinese. In addition to its chairman’s China roots, the company’s leadership also includes former executives from Ant Group, the financial affiliate of e-commerce giant Alibaba. Instead of exporting a cookie-cutter product, OPay adapted China’s super-app playbook, similar to Ant’s popular Alipay, to solve specific pain points in Nigeria.
While it may have some China background, OPay also emphasizes that it has no financial links to the Chinese market, saying it believes its U.S. listing doesn’t require approval from the Chinese securities regulator. Its decision to base itself in Singapore mirrors a growing movement by Chinese fintech entrepreneurs eschewing their heavily regulated home market to pursue their fortunes in more lightly regulated regions.
OPay’s reported $500 million fundraising target implies a market capitalization of roughly $4 billion. That values the company at more than 20 times its annualized net profit for 2026 — roughly in line with Latin American digital banking heavyweight Nu Holdings (NU), which has a similar emerging-market credit and payment focus.
By choosing the road less traveled, OPay bypassed the Southeast Asian squeeze and built an enviable franchise in one of the world’s most underbanked markets. If its IPO succeeds, it will prove that for fintechs with the right execution model, the most lucrative opportunities are sometimes found furthest from home.
To subscribe to Bamboo Works weekly free newsletter, click here
Related Articles
RELATED ARTICLES
-
Yiren Digital left in the cold after parent freezes $4.4 billion in wealth products
 YRD.US
- Declawed in China, UP Fintech faces challenges in global marketplace
-
Digital China’s AI reboot gets stuck in its low-margin past
0861.HK
- For Futu and UP Fintech, regulatory bombshell may finally clear global path forward
-
Wall Street renaissance for China stocks? DSC listing offers mixed picture
DSC.US
- Chinese ‘Easter Eggs’ fall back to earth after wild year on Wall Street
-
In the digital intelligence battle, Digiwin bets on ancient Greek goddess
300378.SHE